France's rising debt costs are placing significant pressure on the nation's fiscal stability as the government balances social spending with increasing borrowing expenses. Public debt currently stands at approximately 120% of gross domestic product (GDP), leading to a widening risk premium compared to Germany. While the government plans to allocate €4 billion for school renovations and €1 billion for universities, interest payments on total public debt are projected to climb from over €79 billion in 2026 to potentially €132 billion by 2030. This escalating debt service burden occurs amidst political instability and nationwide protests regarding the cost of living.
The widening gap between French and German borrowing costs
The risk premium, or spread, between French and German government bonds has reached its highest level since the financial crisis. Currently, France must pay nearly 1.6 percentage points more in interest than Germany on 10-year bonds. This divergence is driven by France's debt-to-GDP ratio of roughly 120%, which contrasts sharply with Germany's ratio of approximately 65%. While Germany maintains a AAA credit rating and a stable outlook, French credit agencies have assigned ratings ranging from AA to A+ (or Aa3), often accompanied by a negative outlook.
Friedrich Heinemann, an economist at the Leibniz Center for European Economic Research (ZEW) in Mannheim, describes the spread as a "fever gauge" for bond markets. According to Heinemann, if this spread rises too sharply, France's financing conditions come under pressure, which can lead to higher interest rates for anyone in the country needing a loan. He warns that such pressure can cause banks to struggle, potentially escalating into a full financial crisis and a genuine economic collapse.
Comparative Debt Indicators
| Metric | France | Germany |
|---|---|---|
| Debt-to-GDP Ratio | ~120% | ~65% |
| Credit Rating | AA / A+ / Aa3 | AAA |
| 10-Year Bond Spread | +1.6% over Germany | Baseline |
| Outlook | Negative (various agencies) | Stable |
Projected trajectory of French interest payments
France is facing a massive surge in the portion of its national budget required to service existing debt. The central government's interest bill alone is currently estimated at €62.6 billion by the Agence France Tresor, a French Treasury agency. However, when including the costs incurred by social security funds and local authorities, the total financial burden is expected to grow significantly over the next few years.
According to current projections, the total interest paid on public debt will follow this path:
- 2026: Over €79 billion
- 2027: Exceeding €91 billion
- 2030: Between €125 billion and €132 billion
This escalation is compounded by the need to refinance large amounts of outstanding bonds that were originally issued during periods of historically low interest rates. Because the country maintains a substantial budget deficit, it must simultaneously take on new debt to cover current expenditures, creating a cycle of increasing borrowing requirements.
Social benefits and the political resistance to fiscal reform
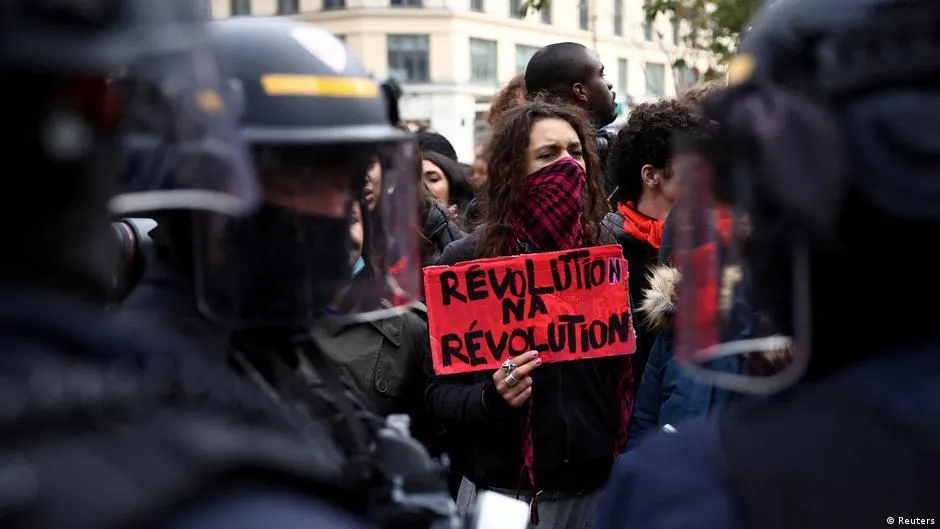
Despite the mounting debt, there is significant domestic pressure to maintain high levels of public spending. The French government has recently proposed spending an additional €4 billion on education through low-interest loans for school renovations by 2030, alongside a €1 billion allocation for universities by 2029. This spending comes at a time of nationwide protests over the rising cost of living.
Landry Charrier, a researcher at the University of Bonn's Center for Advanced Security, Strategic and Integration Studies, suggests that the abstract nature of debt prevents immediate political shifts. According to Charrier, debt remains an abstract concept if its consequences are not felt in daily life. He cites data from INSEE, the French national statistics agency, showing that 56% of the population receives more in government benefits and services than they pay in taxes and social contributions. This creates a tangible interest for a majority of the population in maintaining the status quo.
Charrier further notes that the adoption of the euro has historically softened the pressure to adjust. In previous eras, the devaluation of the French franc would have provided an immediate warning signal through rising prices and declining purchasing power. With the euro, that immediate signal is missing, which can create an illusion that necessary fiscal adjustments can be postponed indefinitely.
Political polarization and the rise of 'economic fairy tales'
The economic reality of France's debt is often sidelined in political discourse by both the far-right and far-left. Major political players are campaigning on platforms that include costly promises without clear funding mechanisms. For example, Marine Le Pen, leader of the National Rally (RN), has proposed reinstating the retirement age of 62 while promising €140 billion in savings. On the other end of the spectrum, Jean-Luc Melenchon, leader of France Unbowed (LFI), has suggested that government bonds held by the French central bank should be "thrown into the fire," claiming that "nobody will ever notice they've disappeared."
Friedrich Heinemann characterizes these positions as "economic fairy tales" told by radical parties on both sides of the aisle. According to Heinemann, the commonality between these political messages is the claim that there is a way to resolve the fiscal crisis without requiring either fiscal consolidation or painful budget cuts.
The political landscape of fiscal promises
- National Rally (RN): Proposes lowering the retirement age to 62; targets €140 billion in savings.
- France Unbowed (LFI): Suggests unconventional handling of central bank-held bonds to mitigate debt.
- Current Government: Operating without a parliamentary majority and facing high debt-to-GDP levels.
Broader implications for the German economy and Europe
While the focus remains on France, the trend of rising interest costs is also beginning to impact Germany. Although Germany currently maintains a much stronger fiscal position, the ZEW's Heinemann has calculated that German interest payments are likely to increase sharply by the early 2030s. As both debt levels and interest rates rise, the German federal government's annual interest payments, which have stood at approximately €30 billion, could triple within a few years.
Heinemann warns that German interest payments could eventually exceed €90 billion, with the €100 billion mark in the federal budget becoming a foreseeable reality. This suggests that the fiscal pressures currently central to the French crisis may eventually become a systemic concern across the eurozone, particularly as nations navigate the transition from low-interest environments to higher-cost borrowing regimes.